This article defines leverage in real estate investment. It explains that positive leverage occurs when a property’s return (cap rate) exceeds the debt cost, thereby increasing the investor's yield. Negative leverage occurs when debt costs exceed the property’s return, reducing yield and increasing risk.

Debt can make a strong real estate deal better. It can also make a fragile deal look healthier than it is.
For years, low borrowing costs made leverage easier to understand. If a property’s yield exceeded its interest rate, debt often boosted returns. Today, investors need to look deeper.
At RockStep Capital, we consider the interest rate alongside the loan’s amortization, annual debt service, maturity, and the durability of the property’s net operating income.
Positive leverage boosts an investor’s return on equity, while negative leverage decreases it, even if the property makes loan payments. Understanding this helps determine if debt supports or harms the investment.
What Is Leverage in Commercial Real Estate?
In commercial real estate, leverage means using borrowed capital to purchase or improve an investment property.
Leverage enables investors to acquire more real estate by combining their equity with lender debt. To understand the debt's position relative to investor equity, consult RockStep Capital’s guide to the commercial real estate capital stack.
An investor plans to buy a $1 million property, contributing $300,000, with a lender providing $700,000. The $700,000 loan is leverage for the purchase.
Debt acts as a financial amplifier. If property returns exceed financing costs, leverage boosts equity return. If debt is too expensive, it reduces cash flow and increases risk.
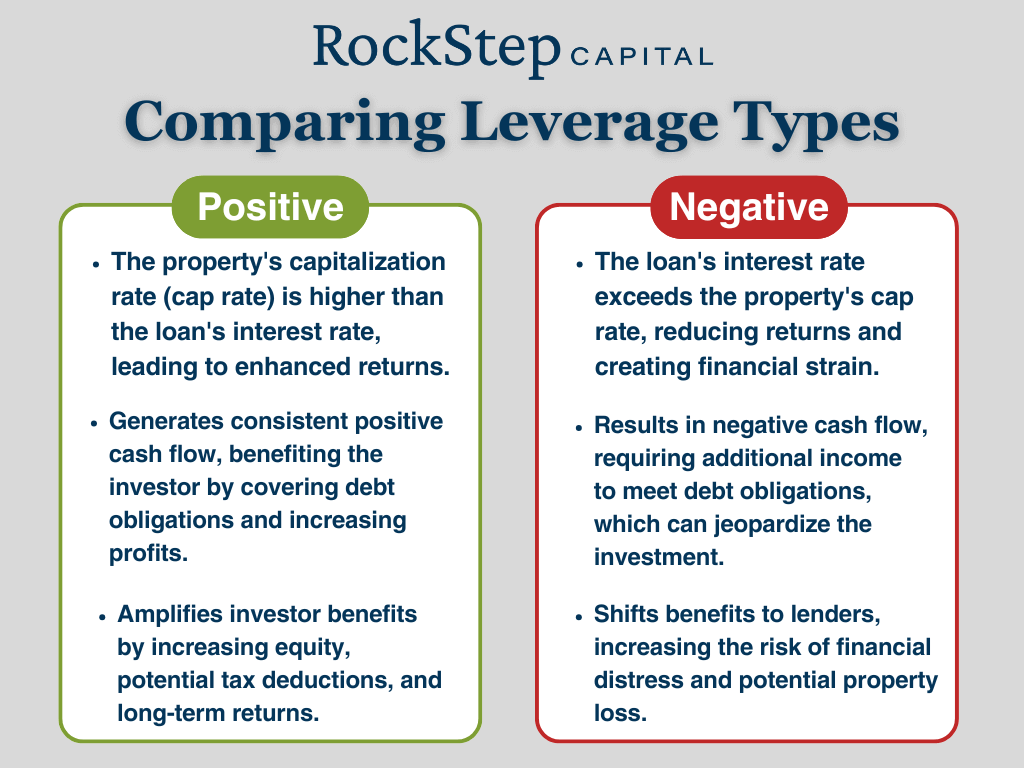
Before we dive into comparing positive and negative leverage, check out the following graphic for a brief overview of the main differences between these two types of leverage.
What Is Positive Leverage in Commercial Real Estate?
Positive leverage occurs when using debt increases the return earned on the investor’s equity compared with the property’s return without debt.
How Cap Rate Helps Measure Positive Leverage
A property’s capitalization rate, or cap rate, is a useful place to start:
Cap rate = Annual net operating income ÷ Purchase price
Net operating income (NOI) is a property’s effective gross income minus operating expenses, calculated before debt service, taxes, depreciation, amortization, and most capital costs.
Why the Loan Constant Matters in Commercial Real Estate
Investors compare a property’s cap rate to the loan’s interest rate for a quick initial impression, especially with interest-only debt, but it doesn't reveal the full story.
If the loan amortizes, each payment covers principal and interest, so the property must cover both, meaning the loan’s annual cash burden can surpass its stated interest rate. For amortizing loans, compare the property’s unlevered yield to the loan constant.
Loan constant = Annual debt service ÷ Original loan amount
The loan constant shows annual principal and interest as a percentage of the original loan, helping investors determine whether debt enhances equity return through levered cash-on-cash return.
A Positive-Leverage Example
Imagine a shopping center with the following terms:
- Purchase price: $5 million
- Annual NOI: $400,000
- Loan amount: $3.25 million
- Investor equity: $1.75 million
- Interest rate: 6.25%
- Amortization period: 30 years
- Annual debt service: approximately $240,130
First, calculate the property’s cap rate:
$400,000 ÷ $5,000,000 = 8.0%
Next, calculate the loan constant:
$240,130 ÷ $3,250,000 = 7.39%
After paying annual debt service, the property produces approximately $159,870 in pre-tax cash flow. The levered cash-on-cash return is:
$159,870 ÷ $1,750,000 = 9.14%
Without debt, the property produces an 8.0% yield. With debt, the investor earns a 9.14% cash-on-cash return on the contributed equity.
The financing improves the current equity return. That is positive leverage.
What Is Negative Leverage in Commercial Real Estate?
Negative leverage happens when debt lowers investor equity returns, turning into a headwind. Instead of boosting returns, loan costs eat into cash flow.
Consider the same $5 million shopping center and financing, but with an annual NOI of only $275,000.
The cap rate would be:
$275,000 ÷ $5,000,000 = 5.5%
After approximately $240,130 of annual debt service, only about $34,870 remains in pre-tax cash flow. The levered cash-on-cash return becomes:
$34,870 ÷ $1,750,000 = 1.99%
The property produces a 5.5% unlevered yield, but the debt reduces the investor’s current equity return to approximately 1.99%.
That is negative leverage.
This example shows an important distinction: the property generates enough NOI to cover loan payments, but financing leaves little cash flow for investors.
A deal can cover its debt and still be negatively leveraged.
Positive Leverage vs. Debt Service Coverage Ratio
Positive leverage and debt service coverage ratio, or DSCR, are closely related, but they answer different questions.
DSCR = Annual NOI ÷ Annual debt service
DSCR measures whether a property generates enough NOI to cover its required loan payments.
A DSCR of 1.0 means the property’s NOI equals its annual debt service. A ratio above 1.0 indicates positive cash flow after debt. Below 1.0 means the property can't cover its debt.
In the negative-leverage example above, the property’s DSCR is approximately 1.15:
$275,000 ÷ $240,130 = 1.15
The property covers the loan, but the deal has negative leverage, reducing the investor’s equity return from 5.5% to about 1.99%. Investors shouldn't rely on one metric; DSCR shows debt-paying ability, while leverage analysis indicates if debt improves or weakens returns.
Positive Leverage Is Helpful, but It Does Not Make a Deal Safe
Positive leverage indicates strong cash flow, as financing boosts equity returns while maintaining healthy debt coverage and strengthening investors' foundation.
Still, positive leverage cannot rescue a weak property or guarantee a successful investment.
How Overleveraging Increases Commercial Real Estate Risk
More debt can boost returns when property income and values rise but can worsen problems if NOI falls, tenants leave, expenses increase, or major capital needs emerge.
Overleveraging is risky because high-loan properties have little margin for error. Even a slight NOI decline could pressure distributions, reduce DSCR, or hinder obligations.
Why Loan Paydown Does Not Guarantee Property Appreciation
Investors shouldn't assume property will automatically appreciate as the loan is repaid. While principal payments reduce the balance and build equity, appreciation depends on NOI, property condition, market prices, capital improvements, and future buyers' willingness to pay.
Interest expense can lower taxable property income based on tax rules and investment structure. Investors should consult a tax professional to understand how it applies.
Positive leverage helps the math, but the property still has to perform.
Can Negative Leverage Ever Be Intentional?
Negative leverage is a warning sign but not always a deal breaker. An experienced sponsor may accept temporary negative leverage if there's a credible, well-funded plan to increase NOI.
For example, a shopping center might have signed leases not yet paying rent, with scheduled rent increases, vacant space under negotiation, or redevelopment expected to boost income.
In those situations, the negative leverage may be part of a defined business plan rather than a permanent feature of the investment.
The critical question is what must happen to reverse it.
Credible evidence should support the answer, such as executed leases, realistic rental rates, current construction estimates, adequate reserves, and sufficient time before the loan matures. If the plan takes longer, the property should still operate.
How to Evaluate Leverage Before Investing
Don't leave whether a deal starts with positive or negative leverage to guesswork. Investors should conduct careful due diligence and examine the full loan structure rather than focusing on one attractive rate.
Commercial Real Estate Loan Metrics Investors Should Review
Important factors include:
- Loan-to-value ratio: A higher LTV generally increases financial risk because more of the purchase is financed with debt. The right level depends on income stability, reserves, loan terms, and the business plan.
- Loan constant: For amortizing debt, the loan constant captures the annual principal and interest burden more completely than the interest rate alone.
- Interest-rate structure: Fixed-rate debt can reduce exposure to future rate increases. With floating-rate debt, investors should examine the benchmark, spread, rate cap, and the cost of extending or replacing that cap.
- Amortization and interest-only periods: Interest-only financing may improve early cash flow, but required payments can increase once amortization begins.
- DSCR: Investors should evaluate debt coverage at acquisition and under reasonable downside scenarios.
- Loan maturity: A sound property can still struggle if its loan matures when financing is expensive or hard to obtain.
- NOI durability: Tenant rollover, vacancy, operating expenses, tenant-improvement costs, and capital expenditures can all affect the property’s ability to support debt.
- Loan terms: Recourse provisions, reserves, covenants, extension options, and prepayment penalties can materially change the investment’s risk.
How to Stress-Test a Leveraged Real Estate Investment
Investors should also ask what happens if NOI declines, leasing takes longer, expenses rise, or refinancing terms are less favorable than projected. This is where sensitivity analysis becomes especially valuable. Changing a few key assumptions can reveal whether an investment is durable or overly dependent on everything going right.
Why This Matters for Real Estate Investors
Passive investors need not calculate every loan payment but should evaluate if debt supports or pressures the investment. A projected return may seem attractive, but costly or highly amortizing debt can drain cash flow.
Ask the sponsor for the loan’s interest rate, amortization period, annual debt service, loan constant, DSCR, maturity date, and interest-only period. Then ask whether the projected equity return still holds if NOI drops, leasing is delayed, or refinancing is costly.
Positive leverage boosts a credible business plan, but it can't fix weak property fundamentals. Negative leverage might be manageable temporarily, but investors must know what's needed to reverse it and whether capital is available if improvement takes longer.
The better question isn't whether the deal uses debt, but whether it lets the property perform when the plan doesn't unfold perfectly.
Frequently Asked Questions About Positive and Negative Leverage
“What Is Positive Leverage in Real Estate?”
Positive leverage occurs when borrowed capital increases the return earned on an investor’s equity. This generally happens when the property’s unlevered yield exceeds the full annual cost of the debt.
“What Is Negative Leverage in Real Estate?”
Negative leverage occurs when financing reduces the investor’s equity return. The property may still cover its loan payments, but too much income goes toward debt service, reducing the return on invested equity.
“How Do You Calculate Positive Leverage?”
Start by calculating the property’s unlevered yield and the loan constant. Then calculate the levered cash-on-cash return. If the levered cash-on-cash return exceeds the unlevered yield, the financing creates positive leverage.
“Should Investors Compare the Cap Rate With the Interest Rate or Loan Constant?”
For interest-only debt, comparing the cap rate with the interest rate can provide a useful starting point. For amortizing debt, the loan constant is more accurate because it includes both interest and scheduled principal payments.
“Can a Property Have Positive DSCR and Negative Leverage?”
Yes. A property can generate enough NOI to cover its debt service while the loan still reduces the return earned on investor equity. DSCR measures debt coverage, while leverage analysis measures debt's effect on equity return.
“Is Negative Leverage Always a Bad Investment?”
Not necessarily. A sponsor may accept temporary negative leverage when a credible path exists to increase NOI through signed leases, contractual rent growth, lease-up, or redevelopment. Investors should understand what will reverse the negative leverage and what happens if the plan takes longer than expected.
When Debt Supports the Real Estate Investment
Leverage strengthens commercial real estate investments when income and financing align properly.
Positive leverage boosts cash flow and equity returns, while negative leverage narrows error margins and relies more on future NOI growth, refinancing, or appreciation.
Neither one tells the full story. Investors should examine the loan constant, cash-on-cash return, DSCR, maturity risk, and NOI durability. They must understand what must go right, what could go wrong, and whether the deal can perform if plans take longer.
Debt should facilitate investment, not cause more issues. The best leverage offers a credible path to return before future growth or appreciation.
Topics: